
Caesars Entertainment shareholders voted overwhelmingly to approve a $17.6 billion merger with Fertitta Gaming, clearing a major hurdle toward creating one of the largest gaming empires in the country. The vote took place in Reno, Nevada, ending months of boardroom drama that included a failed rival bid from activist investor Carl Icahn. Under the deal, shareholders will receive $31 in cash for each share they own, and Caesars will become a privately held company once the transaction closes.
The vote count, revealed in a Wednesday SEC filing, showed just how lopsided the outcome was: shareholders cast over 133 million votes in favor of the merger against roughly 4 million votes opposed, according to KTNV. A separate SEC filing detailed the mechanics behind that tally, showing 143.28 million shares were represented at the Reno meeting — a 70.3% quorum — and that the 133.31 million votes in favor amounted to 65.4% of all outstanding shares as of the August 21 record date, according to a Caesars SEC filing. Since approval required a simple majority of all outstanding shares, not just those present, the margin left little room for doubt.
A Bidding War That Fizzled Out
The merger, first announced in May, was not without competition. Icahn had put forward a competing $34-per-share bid for Caesars, but abandoned the offer in mid-September after failing to secure finalized financing terms, according to Gaming America. Two Icahn-appointed directors resigned from Caesars' board on September 16 and waived their rights to name replacements, days before the shareholder vote. Icahn's involvement with Caesars also included the competing bid he later abandoned.
The $31-per-share all-cash offer represented a 49% premium over Caesars' unaffected stock price on February 25, and the agreement included a 45-day go-shop period through July 11 that produced no superior binding bids, the same filing notes. Caesars stock will be delisted from NASDAQ once the deal closes. Under the terms, Fertitta Gaming agreed to pay $5.7 billion for the merger while taking on close to $12 billion in Caesars debt, bringing the deal's total value to about $17.6 billion.
Founders Betting on the Combined Company
Founders Betting on the Combined Company Not everyone is cashing out entirely. The Carano family, which owns roughly 5% of Caesars stock through Recreational Enterprises Inc., agreed to roll a portion of their equity into Fertitta Entertainment rather than take an all-cash payout. The family will retain an investment in Fertitta Entertainment. Caesars' top executive leadership — CEO Tom Reeg, CFO Bret Yunker, and President and COO Anthony Carano — is set to remain in place after the take-private transaction closes, per Gaming America's reporting.
Regulators Still Have the Final Say
Regulators Still Have the Final Say Even with shareholders on board, Caesars and Fertitta Gaming must still complete the federal antitrust review process. The Federal Trade Commission issued a “Second Request” under the Hart-Scott-Rodino Act in September, seeking additional disclosures on potential market overlaps in cities including Atlantic City, Lake Tahoe, and Laughlin, according to 13D Monitor. Those potential market overlaps remain a focus of the review.
The merger contract also addresses delays in completing the transaction. State-level approvals have already begun moving forward: in July, Nevada regulators granted unanimous suitability approvals to two key Fertitta executives, Chief Financial Officer Richard Liem and General Counsel Steven Scheinthal, according to Hotel Dive. Liem and Scheinthal sit on Fertitta's three-member board alongside Paige Farwell Fertitta.
A Sprawling Empire Under One Roof
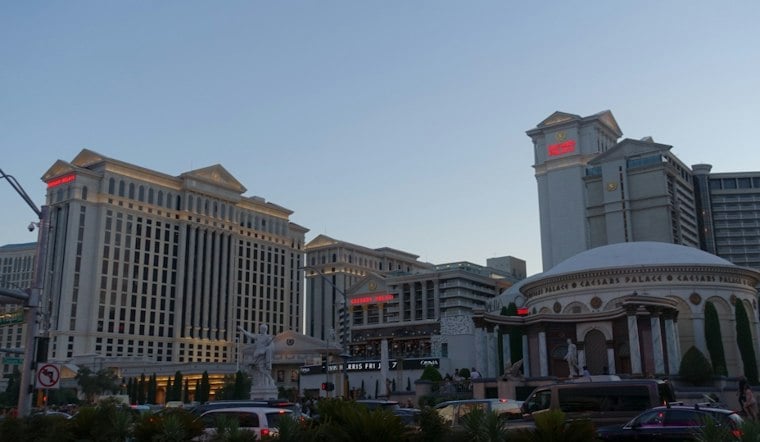
Caesars operates Caesars Palace, the Flamingo, and Harrah's on the Las Vegas Strip, along with casino resorts across the United States. Fertitta, for his part, owns the Golden Nugget in Las Vegas as well as the Rainforest Cafe and Morton's restaurant chains, and he holds the largest shareholder stakes in both Wynn Resorts and DraftKings. Once combined, the merged entity will bring together 60 casino resorts, more than 200 William Hill sports betting venues, and 600 Fertitta dining and entertainment outlets under the unified Caesars Rewards loyalty network.
Fertitta himself stepped back from his role as president and director of Fertitta Gaming. The Houston Chronicle reported that he would resign as Landry's CEO if confirmed. He was nominated for the post by Donald Trump in December 2024 and confirmed in an 83-14 Senate vote on April 29, 2025. The formal merger agreement was reached in May.