
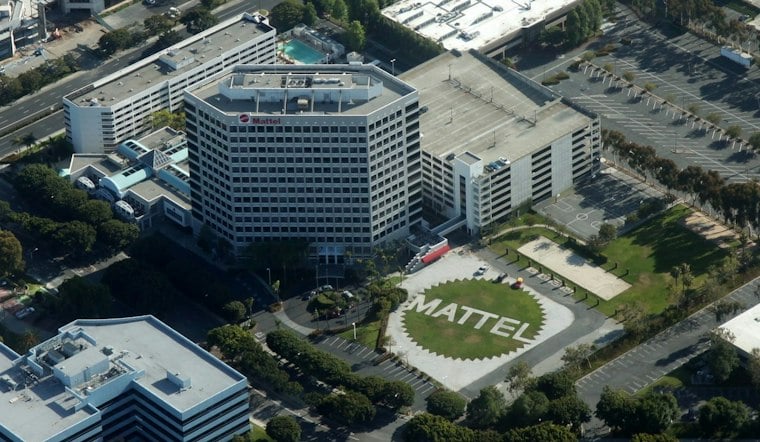
Mattel shares fell about 3 percent after a major shareholder publicly urged the Barbie maker to weigh selling itself, merging with a rival or shedding significant assets. Ariel Investments, which owns a 5.4 percent stake in the toy giant, said in a letter that Mattel's stock remains significantly undervalued and that a strategic buyer would likely pay a hefty premium over the company's current share price.
According to CNBC, Ariel's letter laid out options ranging from a divestiture of significant assets to a merger or an outright sale of the company, arguing that Mattel's portfolio could appeal to toy companies, entertainment companies and private equity firms alike. Mattel responded that its board and management will consider the views expressed in Ariel Investments' letter, as well as the views of the company's other shareholders, and said it would act in the best interests of all shareholders. The pressure lands squarely on Roger Lynch, who is set to become CEO, succeeding Ynon Kreiz.
A Second Shareholder Piles On
Ariel isn't the first big investor to push Mattel toward a shakeup this year. Southeastern Asset Management, which said in an open letter dated May 7, 2026 that it manages more than 4 percent of Mattel's common stock on behalf of clients, had already called on the company to explore strategic alternatives. Per the filing detailed by StockTitan, Southeastern argued there are at least three groups of buyers that would be better owners of Mattel than Mattel itself, pointing to private-equity firms, toy companies including Hasbro, and large media companies.
The investor pressure also follows reported takeover interest from Authentic Brands Group. As reported by Reuters, Mattel has attracted takeover interest from the group. CNBC reported that a potential offer was valued at about $6 billion. Mattel currently trades at $15.65.
Mixed Financial Signals
Mattel's business has sent conflicting signals in recent months. Reuters reported that the company topped first-quarter sales estimates, posting net sales of $862.2 million against analyst expectations of $804.7 million, and raised its full-year adjusted earnings-per-share guidance to a range of $1.27 to $1.39 from an earlier $1.18 to $1.30.
CNBC has reported declining sales and profitability. Mattel has also leaned into growing its IP-driven play and family entertainment business, including plans to invest about $110 million in 2026 primarily in digital games, plus roughly $40 million in performance-based marketing.
Mattel's Stock Decline
CNBC reported shares are down 19 percent since the beginning of the year. The decline stands in contrast to rival Hasbro, whose digital pivot has fared better with investors; Hasbro shares rose as much as 9 percent after its 2026 forecast, bolstered by an 86 percent jump in its Wizards of the Coast and Digital Gaming segment revenue and a 141 percent surge in Magic: The Gathering sales, according to Reuters.