
West Palm Beach has given developer Cohen Brothers Realty a new deadline of January 1, 2029 to finish West Palm Point, the long-stalled 25-story office tower planned for downtown's South Quadrille Boulevard. The extension comes with a catch: the company now has just 30 days to lock down the construction loan it needs to actually break ground.
The city's decision, reported by The Real Deal, follows years of setbacks for the 400,000-square-foot project at 850 South Quadrille Boulevard. Cohen Brothers Realty leased the 2.4-acre site from the West Palm Beach Community Redevelopment Agency back in 2020, but construction has stalled for years since, according to the outlet's earlier reporting on the region's top construction permits. The developer requested the extension to push the completion target to 2029, and the city agreed to set that new date.
Financing Still Hinges on a 30-Day Clock
Lendlease is expected to provide Cohen Brothers Realty with a $300 million construction loan, per the same Real Deal report, but the developer has only 30 days from the deadline decision to actually secure that financing. Rent and property taxes tied to the site will remain in effect until West Palm Point receives its certificate of occupancy, adding financial pressure regardless of when construction wraps. Cohen Brothers has attributed the project's delays to road and de-watering permit issues, the outlet reports.
The company also faced a foreclosure lawsuit tied to the site: Union Labor Life Insurance Company alleged that a Cohen Brothers affiliate had defaulted on a $10 million loan, The Real Deal reported in July. A judge dismissed that suit in January 2026 at the request of both parties, according to Discover South Florida. Separately, West Palm Beach told Cohen Brothers Realty it was in default on its 49-year lease in November 2024, and the city sent a second letter of default in February 2026.
What the Finished Tower Would Include
West Palm Point's design calls for more than 11,000 square feet of retail space, a rooftop park and a gym, along with an attached parking garage that The Real Deal's latest report describes as 10 stories. Discover South Florida's earlier account described the garage as 11 stories with about 1,250 parking spaces, a discrepancy that has not been resolved between the two outlets. A $180 million commercial permit was issued for the project in July 2026, according to Discover South Florida, and Palm Beach County records show the developer started the permitting process this year, per The Real Deal.
Leasing activity suggests real demand despite the delays. Discover South Florida reports that the building's 15,950-square-foot top floor is already leased, its 24th floor is reserved, and letters of intent cover the fourth floor along with floors 11 through 16 — putting roughly a quarter of the tower spoken for before a shovel has hit the ground.
A Crowded Downtown Office Race
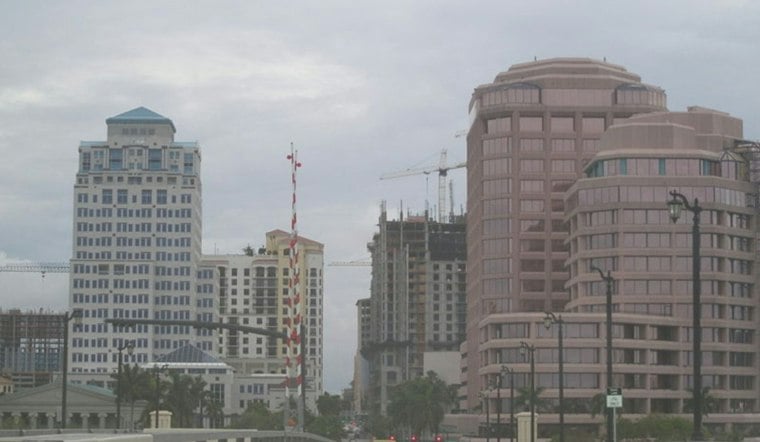
West Palm Point would land in a downtown office market that has drawn major competition in recent years. Related Ross secured a $772 million construction financing package in December for its planned 10 CityPlace and 15 CityPlace towers, according to Florida YIMBY. The two buildings are planned at 470,000 and 490,000 square feet respectively and are expected to add nearly one million square feet of new office space to downtown when completed in 2027.
Other downtown towers have already found tenants. One Flagler and 360 Rosemary are completed and fully leased, while Two CityPlace is under construction and set for 2027, per Discover South Florida. Downtown West Palm Beach has emerged as an office market winner in recent years, The Real Deal has reported, a shift tied in part to Steve Ross's office-building purchases and development in the area — even as leasing and vacancy rates across South Florida overall have remained relatively flat compared with 2019.
For now, West Palm Point's fate rests on whether Cohen Brothers Realty can close its financing within the newly imposed 30-day window. The extended 2029 deadline gives the project room to finally rise, but the company's history of permitting delays and lease disputes means the clock is once again ticking.