
Accelevation, a data-center infrastructure company based in Miamisburg, Ohio, is seeking a Nasdaq listing that could value the business at as much as $5.37 billion. The proposed offering would consist of 30 million shares priced at $20 to $24 apiece, potentially raising up to $720 million, with the company expecting to trade under the ticker ACCV, according to the Miami Herald and Seeking Alpha.
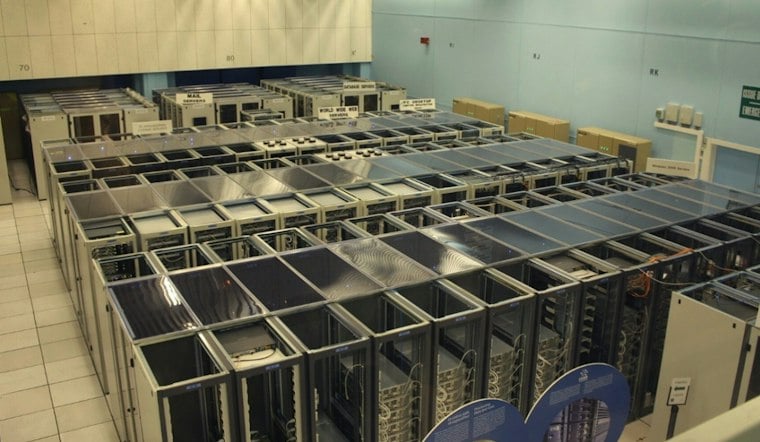
The proposed listing would put an Ohio-based manufacturer into a market increasingly focused on the physical requirements of artificial-intelligence computing. Accelevation designs, manufactures and installs power-distribution and cooling systems for data centers—equipment that sits between a facility’s computing demand and the electricity and thermal-management systems needed to keep it operating.
Growth has accelerated, but the balance sheet remains part of the story
Accelevation reported $447.8 million in 2025 revenue, a 147% increase from 2024, and net income of $21.75 million. Its reported order backlog was about $1.1 billion as of June 30, reflecting demand for equipment that can have long delivery timelines as data-center developers expand capacity.
The offering is not solely a capital raise for new investment. Accelevation is selling 8,635,165 primary shares, while Olympus Partners and other existing stockholders are selling 21,364,835 secondary shares. Proceeds from the primary shares are expected to move to Accelevation Holdings LLC for debt repayment, transaction costs and general corporate purposes; the company has described debt refinancing as the principal use, according to the Miami Herald. Olympus is expected to retain about 85% of the combined voting power after the offering.
That structure gives investors two separate facts to weigh: the reported growth in Accelevation’s operating business and the financial benefits of reducing debt. It also means most shares in the proposed sale would come from existing owners rather than from newly issued stock.
Why the infrastructure market is expanding
The demand backdrop is tied to the scale and operating intensity of data centers, not simply to the number of facilities being announced. The U.S. Department of Energy, citing the Electric Power Research Institute, estimates that data centers could consume up to 9% of U.S. electricity generation annually by 2030, compared with 4% of total load in 2023. That is a national projection rather than a list of confirmed projects or contracted power demand.
The Department of Energy also says data-center electricity demand is growing rapidly, varies by region and can require firm power because facilities operate continuously. Those characteristics help explain the addressable market for Accelevation’s power-distribution and cooling systems, while also underscoring why the timing of individual projects, available grid capacity and local permitting remain important uncertainties. The department’s analysis does not establish that every projected data-center load will be built or that all of it will translate into Accelevation orders.
An Ohio manufacturing company exposed to a broader cycle
Accelevation’s Miamisburg headquarters gives the proposed listing an Ohio manufacturing angle, but its business is tied to a national and global construction cycle. The company’s infrastructure work depends on developers proceeding with data-center projects, customers securing power and financing, and suppliers delivering equipment on schedule.
That dependence is not unique to Accelevation. Vertiv, an established data-center infrastructure supplier, warned in its 2025 annual report that its business relies on continued growth in customers’ data-center and communications infrastructure, and that a slowdown could reduce demand for its products. The comparison does not establish that Accelevation faces the same financial or customer profile, but it illustrates the central limitation of the sector: the same expansion cycle that creates a large backlog can also make suppliers vulnerable if construction plans or capital spending slow. Vertiv’s filing identifies that exposure as a material business risk.
The Olympus-backed company’s proposed Nasdaq debut therefore offers investors a direct way to participate in the equipment layer of the AI buildout, but not a guarantee that projected electricity demand will become revenue. The offering’s eventual pricing, the final share mix and the market’s assessment of Accelevation’s backlog and debt will determine how much of the growth story is reflected in the public valuation.