A proposed life sciences tower planned for a block just south of Moynihan Train Hall has stalled out entirely, and now its lender wants to foreclose. Quinlan Development Group filed suit in New York County Supreme Court on October 13 seeking permission to foreclose on the leasehold interest at 320 W. 31st St., alleging that Cannon Hill Capital Partners affiliate Maple 1 Farley Owner LLC defaulted on a $54 million mortgage used to finance the site.
The site was once envisioned as a 156,000-square-foot lab and office building, an 11-story structure combining research and workspace, according to Bisnow. Architecture firm SGA designed the proposed tower with an undulating massing inspired by the adjacent rail tracks, Passive House-quality energy standards, and cantilevered green terraces. None of it was ever built, and the project never advanced past the planning stage.
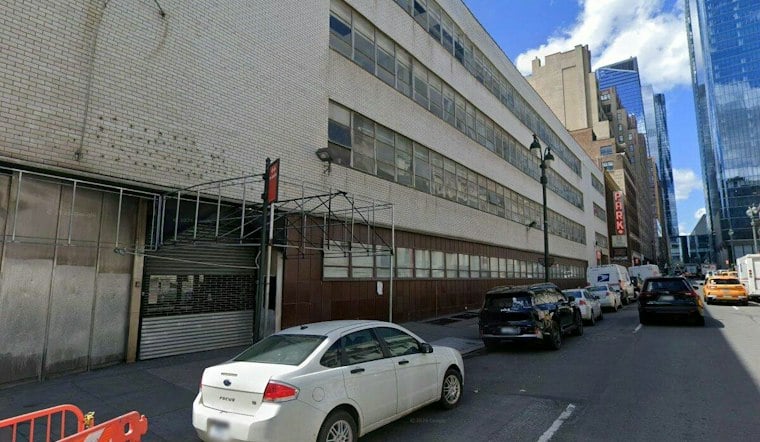
Instead, the old four-story, 116,000-square-foot building that has occupied the 25,912-square-foot parcel since 1953 is still standing. That structure served for decades as the campus of Technical Career Institutes, commonly known as TCI College, until the school ceased operations in September 2017, according to The Real Deal. Touro College also used the building as part of its campus, and as of April 2026 the former Touro campus building still remained on the site, per the Bisnow report.
A Tangled Chain of Ownership and Debt
The project's roots trace to a competitive Manhattan real estate market in flux. Normandy Real Estate Partners originally contracted to buy the 320 W. 31st St. leasehold for $88 million back in November 2019. That deal shifted: Columbia Property Trust ultimately acquired the ground lease from an Onyx Equities-managed entity for $88 million in February 2020, financing the purchase with a $54 million loan from an SL Green-affiliated entity. Jeff Gronning and Melissa Cosgrove Donohoe were both executives at Normandy Real Estate Partners at the time it was acquired.
That loan changed hands repeatedly in the years since. SL Green's affiliate assigned the loan to Bank of China in June 2021, and the loan's maturity date was later extended to August 18, 2025. The borrower never paid off the mortgage, and Bank of China issued a default notice in September 2025. Bank of China then assigned its full interest in the loan, mortgages, and collateral agreements to a Quinlan-controlled entity on September 17, 2026, setting up the preforeclosure proceedings Quinlan began on October 13.
Cannon Hill Capital Partners, which is based in Chelsea, spun out of Columbia Property Trust in 2022 and took over the funds Columbia Property Trust had acquired with Normandy Real Estate Partners back in 2020. Cannon Hill is named as a defendant and recourse guarantor on the mortgage, and per the complaint, Quinlan has reserved the right to pursue Cannon Hill directly if the foreclosure proceeds don't cover the debt. The total amount owed is $65.9 million, including accrued interest, default interest, and additional charges, according to the complaint.
Receiver Sought Amid Mismanagement Claims
Quinlan's attorneys are seeking appointment of a receiver to collect rents, manage the property, and prevent further deterioration in value. The complaint points to an open environmental control board violation at the property, which Quinlan's attorneys claim is evidence of ongoing mismanagement, per the filing.
Underlying fee ownership of the land itself is a separate matter entirely. Overtime Properties LLC has owned the ground beneath the property since 1998, and the entity is registered to Andrew Edelman, president of Charand Real Estate Associates. Quinlan is foreclosing only on the leasehold mortgage; the ground itself remains Overtime's to own regardless of how the litigation unfolds.
Quinlan's attorneys are seeking a foreclosure auction to satisfy the debt. Quinlan Development Group, Cannon Hill Capital Partners, and Columbia Property Trust did not immediately respond to requests for comment, the Bisnow report noted.
Part of a Wider Lab-Space Reckoning
The default fits a pattern playing out across New York's commercial life sciences sector. New York City's life-sciences vacancy rate was 41.8% at the end of the first quarter of 2025, as speculative developments collided with an oversupply of space and federal research funding cuts, according to Bisnow's broader market coverage. Similar distress has hit other Manhattan projects recently: Beacon Capital surrendered a Hell's Kitchen lab site to lender ACORE through a deed-in-lieu transfer in September, as Hoodline previously reported.
Cannon Hill, meanwhile, remains active elsewhere in Manhattan even as this project unravels. The firm is currently partnered with Skylight Real Estate Partners on an office-to-residential condo conversion at 101 Franklin Street in Tribeca. Whether Quinlan intends to complete SGA's original lab design, pivot the stalled site toward office or residential use, or sell the ground lease outright at auction remains an open question.