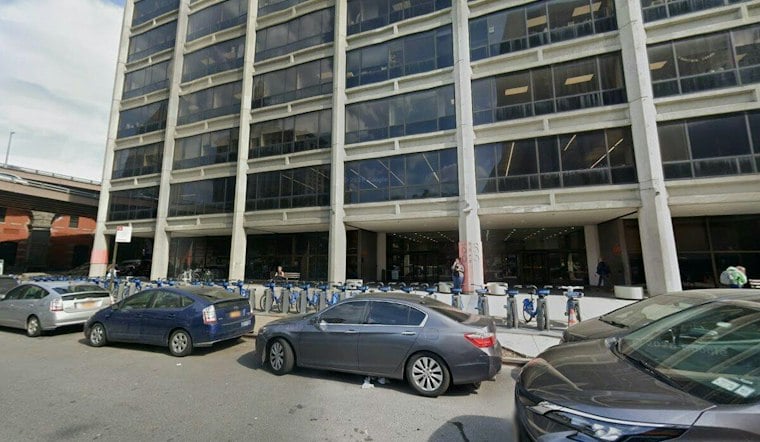
The city-owned office building at 100 Gold Street in Manhattan's Financial District could be torn down and replaced with a sprawling residential complex holding as many as 4,000 apartments, under a plan now moving through city review. The nine-story building currently sits in Lower Manhattan near the Brooklyn Bridge, and officials say its site could soon host some of the tallest residential towers in Lower Manhattan.
Two Towers, One Podium — and a Lot of Housing
The proposal calls for two towers connected at a podium base, according to thecityreporter.nyc, which reports the project could contain as many as 4,000 total apartments. The outlet describes one tower rising to about 115 stories and the other to roughly 78 stories, with the taller structure's reported height of around 1,250 feet comparable to the Empire State Building measured from ground to roof. A separate account from newyorkyimby.com describes the project instead as a three-tower development, with preliminary renderings suggesting heights of at least 1,000 feet, roughly 800 feet, and 450 to 500 feet — numbers that publication cautions remain subject to review, alongside the final tower count and unit totals.
The project is a partnership between the New York City Economic Development Corporation and GFP Real Estate, which NYCEDC says it selected in December 2025 through a competitive process to lead the redevelopment. NYCEDC's own materials describe the plan as approximately 3,700 units, including about 1,000 permanently affordable, rent-stabilized units. A later version of the plan, reported by YIMBY, calls for approximately 4,000 homes — roughly 300 more than the earlier version.
What Happens to the Current Building and Its Tenants
The existing structure currently houses the city's Department of Housing Preservation and Development, other city agencies, and a senior center, the city reporter notes. Those agencies are expected to relocate as part of the redevelopment. NYCEDC says the new plan would also include a new older adult center, about 40,000 square feet of public-realm improvements, and a publicly accessible commercial fitness center of similar size.
NYCEDC frames the arrangement as coming at no cost to the city, pointing to a cross-subsidy structure built into the deal. Officials project the development would nearly double the number of permanently affordable homes built in Manhattan Community District 1 over the previous decade — a notable claim given how little affordable housing has landed in the district in recent years. The project traces back to the Manhattan Plan, an initiative from the prior mayoral administration aimed at creating 100,000 new homes across the borough over a decade, according to a 2025 report from newyorkyimby.com.
A Potential Density Record, and a Changed Neighborhood
If built as described, the development could add roughly 8,080 residents to the Financial District and increase the neighborhood's population by about 10 percent, per the same city reporter account. Patrick Kennell was quoted in that report suggesting the project could become what he called “the single most dense — from a dwelling-unit perspective — building in the history of New York City.” The outlet also noted that the planned 4,000 apartments would dwarf unit counts at comparable developments including 25 Water Street, a Midtown project, a Jersey City complex, and a two-tower Chicago development.
Before any shovels hit the ground, the project must clear the city's environmental review process. NYCEDC says the development team is conducting site due diligence and environmental review, with a scoping hearing expected to kick off the formal process, and the agency anticipates the project will enter New York City's Uniform Land Use Review Procedure in 2027. Separately, NYCEDC's project materials state that at least 25 percent of the planned housing units are designated as permanently affordable without public subsidy.