
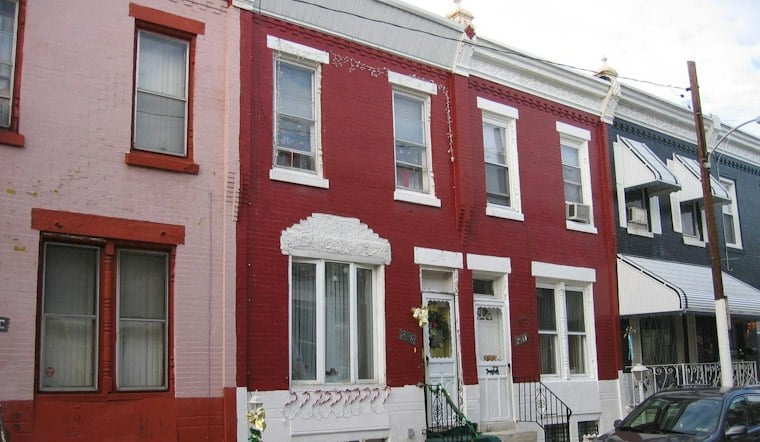
Philadelphia is moving to become the first city in the country with its own mortgage program, and Mayor Cherelle Parker is sharing new details about how it will work. One Philly Mortgage will offer first-time homebuyers a 30-year fixed-rate loan with rates set a full percentage point below current market levels, cap down payments at no more than 3%, and waive private mortgage insurance altogether. City officials are targeting a launch by the end of 2026.
Parker revealed at an Axios Philly live event that the city has secured Citizens Bank as a lender for the program and is in talks with other banks, according to Axios. Normally, borrowers pay private mortgage insurance until their loan balance drops to 80% of the purchase price, but One Philly Mortgage borrowers will skip that cost entirely, since the city will establish a reserve fund to cover lender losses if borrowers default. The Philadelphia Housing Development Corporation describes the program as designed to help low- and moderate-income residents become first-time homeowners by lowering monthly payments through partnerships with local lenders, with public funds covering a portion of the interest.
The program will be open to households earning up to 120% of area median income, a threshold that per the Inquirer runs over $100,000 for a single individual, per Axios. Parker’s administration estimates the no-PMI structure and below-market rate could save a borrower an estimated $3,400 annually on a $200,000 home, according to Axios. Parker told the outlet the initiative is meant to put people on a path to self-sufficiency.
A Housing Plan Years in the Making
Parker first teased the mortgage program in spring 2026 while pitching her $2 billion H.O.M.E. initiative to city lawmakers, an effort that aims to build, preserve or restore 30,000 homes across Philadelphia, per Axios. That plan draws on bonds, local, state and federal funding, and the value of existing city-owned land and property assets. According to WHYY, the proposed first-year budget for H.O.M.E. calls for $194.6 million spread across 26 programs, with $25 million earmarked specifically for One Philly Mortgage to provide reduced down payments and low-interest loans.
WHYY’s reporting shows the broader H.O.M.E. programs are meant to serve households earning roughly 30% to 120% of area median income, with almost one-third of the proposed budget — just under $60 million — dedicated to those earning up to 60% of the area median. NBC Philadelphia reported in September that city data showed Philadelphia a little more than halfway toward its 30,000-unit goal, with about $83.1 million spent of the $277 million City Council had approved for the H.O.M.E. program that year.
Why Philadelphia Needs Help Getting People Into Homes
The push comes as Philadelphia, one of the country's poorest cities, faces an affordable housing crisis amid rising home prices and interest rates, per Axios. The numbers back that up: median homeownership costs in the city more than doubled from 2014 to 2024, according to the Federal Reserve Bank of Philadelphia. Fewer than 40% of homes in the city are now considered affordable to median-income households, down from more than 60% just a decade earlier, the bank's research found.
Philadelphia's homeownership rate itself has slipped, falling from 57.5% in 2005 to 52.4% in 2023, per the same research. The racial gap is stark, too: between 2019 and 2023, Black homeownership in the city sat at 47.4%, compared with 57.4% for White households. The Philadelphia Fed also found that high debt-to-income ratios have been a primary reason for mortgage denials in the city — exactly the kind of barrier One Philly Mortgage is designed to address through its lower rate and reduced down payment.
The Massachusetts Model — and an Economist's Warning
One Philly Mortgage is modeled after Massachusetts' long-running ONE Mortgage program, according to Axios. That program has helped more than 22,000 low- and moderate-income buyers purchase homes since 1990, with about half of those loans going to households of color and roughly two-thirds of the purchased homes located in historically underserved urban neighborhoods, Axios reported. The Massachusetts Housing Partnership notes separately that ONE Mortgage offers 30-year fixed-rate loans held in portfolio by more than 40 participating lenders, requires a minimum down payment of just 3%, and carries no private mortgage insurance cost because lenders retain the credit risk backed by a loan-loss reserve.
But not everyone is convinced Philadelphia can replicate that track record. Kevin Gillen, a Drexel University economist and real estate finance expert, told Axios that the city's high poverty rate and distressed housing stock could make it difficult to match Massachusetts' success. Gillen warned that a short-term bump in homeownership could lead to higher long-term foreclosure rates, and cautioned that borrowers could end up facing costly home maintenance and repairs they cannot afford.
What Comes Next
Despite those concerns, city officials argue the program could open access to cheaper mortgages for buyers who have been locked out of traditional lending, potentially making homeownership more affordable for first-time buyers who struggle to qualify for conventional loans. The Philadelphia Housing Development Corporation notes the program will also include pre- and post-purchase counseling through city-funded housing counseling agencies, though final guidelines and the application process are still being finalized. For now, the agency's own guidance simply tells prospective buyers to check back soon for details on how to apply.