

























































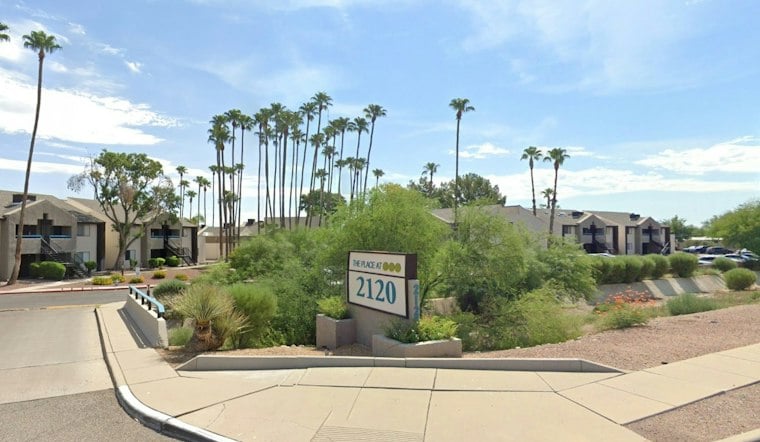
A 202-unit apartment community on Tucson's west side has traded hands for $18.05 million, or $89,356 per unit, adding another data point amid a recent acceleration in Tucson's multifamily sales activity, as NorthMarq's analysis indicates. The Place at 2120 sits on Silverbell Road near Grant Road and Interstate 10, a stretch of the city increasingly tied to new economic development nearby.
Deal Details and the Brokers Behind It
Institutional Property Advisors, a division of Marcus & Millichap, announced the sale, according to Real Estate Daily News. IPA Senior Managing Directors Hamid Panahi and Clint Wadlund represented the seller, The Founders Group, and procured the buyer, AndMark, per the outlet's reporting. The 12-building property offers one-, two- and three-bedroom floor plans and sits on more than seven acres, though sources differ on its construction year — Real Estate Daily News reports the complex was built in 1986, while a listing on apartmentfinder.com puts the construction date at 1987.
Previous ownership upgraded roughly 90% of the unit interiors, the outlet notes, with features including white shaker-style cabinetry, resurfaced countertops, black appliances, and modern lighting and plumbing fixtures. Select floor plans also include vaulted ceilings and linen closets. Community amenities span a swimming pool and spa, a fitness center, a dog park, a laundry facility, and a playground.
Why Brokers Point to the Westside Submarket
Panahi said Tucson's affordability, diversified employment base, and long-term housing demand make the market attractive for multifamily investment, according to the same report. Wadlund tied the appeal more specifically to the surrounding submarket, saying that economic development there — including the forthcoming Casino Del Sol Vahi Taa'am — is quantifiably increasing the employment base while infrastructure improvements boost connectivity, per Real Estate Daily News.
That casino project is set to open at 1055 W. Grant Road on November 15, according to Casino Del Sol. The 153,000-square-foot destination is expected to bring approximately 500 new jobs to Southern Arizona, the casino's own announcement states. Grant Road and Interstate 10 also connect the area to employment hubs throughout Tucson, with Downtown Tucson sitting nearby to the complex and shopping and entertainment options including the Tucson Premium Outlets, Tucson Mall, and La Encantada within reach.
A Market Moving Faster Than It Has in Years
The Place at 2120 sale lands amid a broader acceleration in Tucson multifamily trading. Total sales activity during the first quarter of 2026 exceeded the levels recorded in the first half of each of the prior three years, according to a report from NorthMarq. The median Tucson multifamily sale price climbed to $140,900 per unit in that quarter, up 18% from a year earlier, the firm found — a sharp reversal from 2025, when the median sale price had dipped 18% to $119,900 per unit, per the same source. Most of this year's transactions have clustered in the Central Tucson and East Side submarkets, NorthMarq's analysis shows.
The pace of trading still lags the volume of new supply hitting the market. Roughly 4,800 multifamily units have come online in Tucson since the start of 2023, but only about 200 of those units have actually traded, NorthMarq reports. Deliveries slowed to approximately 700 units in 2025, down considerably from the prior two years' averages, while roughly 2,800 units were slated for completion in 2026, according to the firm's construction outlook.
Vacancy and Supply Pressures Ahead
Those supply dynamics are expected to keep shaping rents and vacancy. Tucson multifamily vacancy was projected to rise 100 basis points annually in 2026, NorthMarq's analysis found, even as a separate report from Marcus & Millichap found that metro-wide vacancy had held steady over the past year, with an expected drop in completions poised to limit further vacancy movement through the rest of 2026. Job growth in the metro has improved from the prior year's losses but remains modest, according to the same report. Construction starts had declined steadily since early 2023.
Other recent Tucson apartment trades illustrate the range of pricing investors have paid for aging, mid-sized complexes. Greenwater Real Estate Management paid $32 million, or $106,312 per unit, for the 301-unit Peaks at Redington, according to CRE News. Break of Day Capital separately paid $33 million, or $110,000 per unit, for the 300-unit River Oaks property, per a less certain account from the same outlet.


