

























































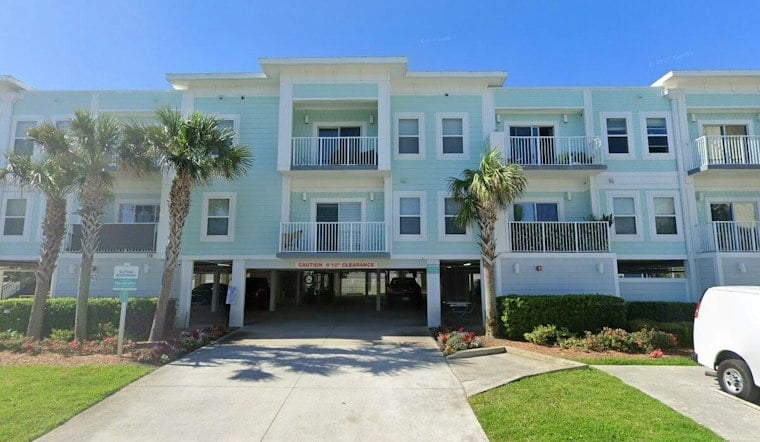
Surfside Apartments in Jacksonville Beach sold for $19 million on Oct. 20, a deal that brokers say set new price benchmarks for the local multifamily market. The 62-unit complex, split across three noncontiguous buildings near the ocean, changed hands after a marketing process that drew 23 property tours and 15 offers.
According to the Jacksonville Daily Record, Oso Capital, acting through Eckstein Investments LLC, sold four properties to Surfside Jax Beach LLC for the $19 million price on Oct. 20. A special warranty deed covering the transaction was recorded with the Duval County Clerk of Court on Oct. 23. The buyer was identified as private equity fund KABR, which is listed as manager of Surfside Jax Beach LLC.
The property itself consists of 62 residential units and one commercial space, and Cushman & Wakefield's own listing for the asset describes it as a 63-unit mixed-use property with 62 multifamily units and a single commercial unit. The firm represented seller Oso Capital and also arranged acquisition financing for the deal with Greystone through a regional bank, the newspaper reported.
Four Parcels, One Complicated Deed
Per the Daily Record, the deed lists four parcels involved in the transaction, even though Cushman & Wakefield identified only three Surfside addresses: 814 1st St. N., 116 2nd Ave. S. and 913 2nd St. S. The fourth parcel is intended to accommodate additional parking for the building at 116 2nd Ave. S., according to the same report.
The buildings sit less than two blocks from the ocean, east of Florida A1A, and were built in 2014 and 2015. That combination of new construction and beach proximity helped drive competitive bidding, the newspaper's account indicates, with the marketing push ultimately narrowing down to four best-and-final offers before a buyer was chosen.
Brokers Point to Scarcity at the Beach
Cushman & Wakefield director William Bruce, who helped represent the seller, attributed the result to the asset's scarcity and the premium investors are willing to pay for quality real estate in Jacksonville's Beaches submarket, per the Daily Record's reporting. The firm also said the sale established new Jacksonville-market benchmarks for price per unit and cap rate, though the specific figures were not disclosed in available reporting.
A separate release covered by YIELDPRO went further, stating that the sale set records across Central and North Florida for transactions completed since the Federal Reserve's first rate hike in March 2022. That framing places the Surfside deal among a small handful of trades considered standout performers in a multifamily investment climate that has been reshaped by years of higher interest rates.
A Market Still Finding Its Footing
The Surfside sale lands in a Jacksonville multifamily market that is still digesting a construction boom. A Q2 2026 report from Matthews found trailing-12-month completions had fallen 50.6% to 3,559 units, down from the 9,217 units delivered at the top of the cycle in 2024. A separate account from the Jacksonville Business Journal similarly described apartment completions dropping 60% from their 2024 peak, though the two reports describe the decline using different measures.
That pullback in new supply has coincided with early signs of stabilization. The same Matthews report found Jacksonville multifamily rents grew 0.64% year over year in the second quarter, the market's first positive reading after three straight years of decline, while net absorption reached 1,564 units, up 31.6% from a year earlier. Units under construction fell to just 2.35% of inventory, down from an 11.64% peak in the first quarter of 2023, the same report noted.
Investment activity has told a more uneven story. Trailing-12-month Jacksonville multifamily investment volume rose 25.6% year over year to $1.15 billion, per Matthews, but the second quarter alone came in at just $120.2 million, down 69.5% from a year earlier. Cap rates, meanwhile, compressed slightly to 5.57%, down from 5.62% a year ago. Cushman & Wakefield's own market tracking separately reported year-to-date net absorption of 2,910 units, even as occupancy remained 210 basis points below year-ago levels, according to the firm's Jacksonville MarketBeat report.
KABR's Bigger Play in the First Coast
The Surfside purchase comes as KABR has been positioning for a broader push into the region. The firm was reported to be raising a $300 million investment fund to fuel its expansion plans, according to the Jacksonville Business Journal. Snapping up a scarce, recently built beachside asset fits that stated ambition to grow its First Coast footprint.
Jacksonville's apartment market has produced headline-grabbing sales before. In 2020, the 350-unit JTB Apartments sold for $83.25 million, or $237,857 per unit, a figure the Daily Record described at the time as a record in the Jacksonville area, eclipsing the previous mark of $228,448 per unit set by the sale of the 348-unit The Elysian. That same report noted the average price per unit for Northeast Florida apartment sales stood at $104,000 in 2019 before climbing to $152,750 during the first half of 2020, underscoring just how much the per-unit math has shifted across multiple cycles.




