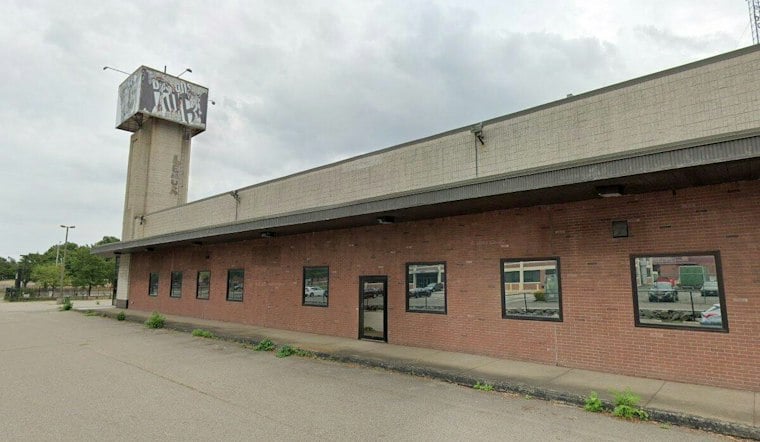
A Boston developer says the partners behind a planned 754-unit apartment complex on Morrissey Boulevard in Dorchester tried to sell the land out from under it, even after city officials signed off on two 18-story towers for the site. Copper Mill filed suit Oct. 15 in Suffolk Superior Court against POB Capital and Pactolus Private Wealth Management, accusing them of fraud, civil conspiracy and several other claims tied to the collapse of their partnership on the 2.2-acre former WLVI-TV property.
According to Banker & Tradesman, Copper Mill agreed in 2024 to buy the site for $67.5 million, with a closing date set for June 30, 2026. The project itself calls for two towers totaling 613,320 square feet and 754 apartments, according to the same report. Boston officials approved the Morrissey Boulevard project in 2025, after Copper Mill took over the lead in securing permits from Center Court Partners in late 2024, per Banker & Tradesman.
How the Partnership Came Together
Copper Mill and its counterparties formed a joint venture on Sept. 4, 2025, with POB Capital and Pactolus holding a combined 64.35 percent stake and Copper Mill holding 35.65 percent, according to the lawsuit as reported by Bisnow. POB Capital CEO Richard Holly had urged Copper Mill CEO Andrew Flynn to pursue the project as a joint venture and pitched a broader push into a series of Boston developments, the suit alleges, emphasizing relationships with Starwood, Brookfield and KKR that could help finance the work.
Copper Mill filed its application with the city in March 2025 outlining two buildings on the 2.2-acre site, including 150 income-restricted units, according to Bisnow's reporting on the complaint. The Boston Planning & Development Agency board approved the proposal that August. Per the lawsuit, Holly later expressed surprise to Flynn about the sheer size of the plans, reportedly telling him that if Copper Mill actually secured approval for a project that large, selling the land for just $67.5 million would make the sellers look like morons.
Allegations of Stalled Financing and a Secret Buyer
The lawsuit alleges that the defendants worked to undermine the joint venture while appearing to support it, failing to arrange financing and refusing to set up meetings between Copper Mill and prospective investors. As reported by Universal Hub, Copper Mill claims POB began deliberately stalling on getting money for the project and then began offering the property, along with its hard-won city approvals, to other real-estate firms. The complaint describes the financing efforts as a sham.
Court filings cited by Bisnow state that POB Capital and Pactolus approached the owner of an unnamed Boston real estate company with a deal valuing the property at $82.5 million, well above the $67.5 million price Copper Mill says it had locked in. The defendants then sent Copper Mill a notice terminating the joint venture agreement on June 30, 2026, the same date originally set for closing, according to the lawsuit.
A Letter, Then Silence
Flynn sent a letter to the defendants on Aug. 13, giving notice of Copper Mill's claims and seeking to resolve the dispute, but the defendants did not respond substantively, according to the suit as detailed by Bisnow. Copper Mill says it now owes significant outstanding balances to third parties who worked on development plans for the project. The complaint, signed by Sheehan Phinney attorneys Aaron Rosenberg, Steven Veenema and Stephanie Hoyer, includes nine counts in total, among them fraud, breach of the implied covenant of good faith and fair dealing, tortious interference with a contract, unjust enrichment and civil conspiracy, along with a violation of the state trade-practices law, per Universal Hub.
Copper Mill is asking the court to force POB Capital and Pactolus to honor the original $67.5 million purchase price and to award unspecified damages to be determined at trial. Copper Mill, POB Capital and Pactolus did not respond to Bisnow's request for comment, that outlet reported. POB Capital is based in Chicago, while Pactolus Private Wealth Management is based in Virginia; Copper Mill is based in Boston.
A Development Landscape Already Under Strain
The fight comes as multifamily construction across Greater Boston sits at a decade-long low, with the city's planning board approving just 3,390 housing units in 2024, down from 7,389 the year before, according to Banker & Tradesman's broader coverage of Copper Mill's regional pipeline. The Morrissey Boulevard project has been described as among the largest housing developments approved in Boston in recent years, according to The Boston Globe, which reported the plans include a three-level, 414-space underground garage, 6,500 square feet of ground-floor retail, and raising the site by five feet to guard against flooding.
Nearby, the long-approved Dorchester Bay City project, cleared in 2023 for nearly 1,957 residential units, had not yet broken ground as of the Globe's reporting, underscoring how slowly even approved Boston megaprojects have moved in this cycle. The Morrissey Boulevard site could also benefit from the state's Opportunity Zone program if the project proceeds, since Gov. Maura Healey included the site on her proposed map for the program's second iteration, which takes effect in 2027.
Copper Mill's CEO, Andrew Flynn, told Banker & Tradesman the company remains committed to the project and to proving its claims in court, framing the Dorchester towers as housing that is needed now, without further delay. The dispute arrives not long after Copper Mill walked away from a separate 502-unit project in Somerville's Davis Square, proposed in January 2026, with the developer saying in August that it was stepping back from that deal and blaming the city for failing to support the project.