
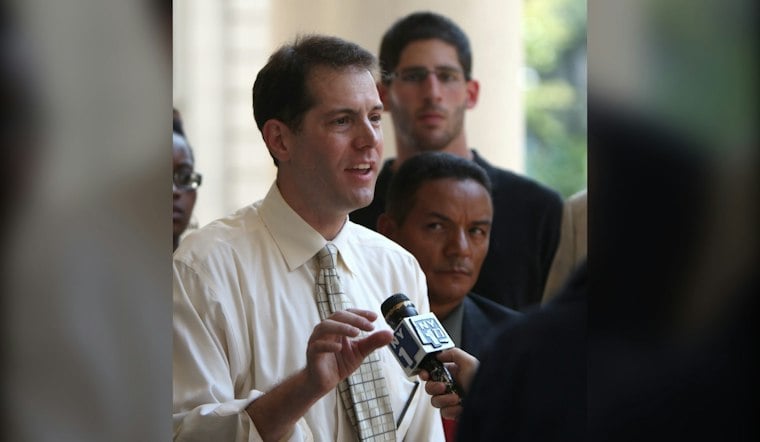
New York City Comptroller Mark Levine has walked away from one of his signature campaign promises: putting city pension money back into Israeli government bonds. Levine said he and his investment team have decided against the purchase, reversing a pledge he made during his 2025 run for office and reaffirmed as recently as April after taking the job.
Levine attributed the reversal to practical, not political, reasons. Because of some technical challenges, and because of financial considerations, he said, this is not an investment that we can make right now, according to The New York Times. His office separately said that when accounting for instability in the region, and the office’s preference for shorter-term bonds, it made sense not to reinvest, per the same report.
The about-face caps a saga that began in 2023, when then-Comptroller Brad Lander let the city’s Israeli bond holdings mature without renewal, a policy the Times describes as a decision that began under his predecessor. Levine, who is Jewish, speaks Hebrew, and has described himself as a staunchly pro-Israel Democrat with friends and relatives in Israel, had promised throughout his campaign to resume those purchases and to reject calls to continue the disinvestment pushed by the boycott, divestment and sanctions movement, which targets Israeli goods.
A Pledge Made Before the Numbers Were In
Levine acknowledged he did not fully understand the financial picture when he pledged to reinvest, and he told the Times he now expects Israeli bond ratings or interest rates to improve within about a year and a half. He described a personal tension behind the reversal, saying, I feel a real closeness to the country, and I’m also heartbroken at the state of politics in the country right now.
The figures involved have varied depending on when and how they were counted. The Times reported the pension system invested roughly $40 million in Israeli bonds at the time Levine was defending the investments, while a separate accounting from the thecityreporter.nyc put the prior city pension holding at no more than $30 million out of $289 billion in total pension assets. Forward reported that New York held Israel Bonds from 1974 until 2023, when Lander ended the city’s investment of $39,947,160 in them.
Beyond bonds, the city’s broader exposure to Israeli assets is also described differently across sources. The Times reported the pension system has over $285 million invested in Israeli companies, while JTA reported the city’s pension system still holds more than $315 million in Israeli assets, primarily in common stocks, after Lander allowed the bond holdings to drop to zero.
Discretion, Boards, and Who Really Decides
Unlike the bulk of the roughly $325 billion pension system, which is controlled by five boards tied to municipal unions including teachers, police officers and firefighters, the comptroller has unilateral discretion over roughly $1.3 billion, the pool that past comptrollers have used to buy Israeli bonds directly. That discretionary authority is what gave Levine room to make — and later break — his promise without needing sign-off from those union-linked boards.
The financial case against Israeli bonds has shifted along with the region's instability. Fitch Ratings lowered its outlook on Israel from stable to negative in April 2024 and had not upgraded it since, the Times reported, while S&P Global and Moody’s both downgraded Israeli bonds during the wars in Gaza, which began in 2023, and Iran, which started in February, before later reversing their outlooks back to stable. Even so, the technical ratings from S&P and Moody’s remain below where they stood in early 2023, according to the Times.
Reuters reported in a separate item that S&P affirmed Israel’s sovereign rating at A/A-1 with a stable outlook in May. On the yield side, two- and three-year Israeli bonds have been returning just over 5 percent, which the Times reported lags the recent performance of New York City’s pension system — even though Levine’s office does hold some bonds with lower returns than that.
A Pattern Playing Out Beyond New York
New York City is something of an outlier. Thecityreporter.nyc reported that New York State’s pension fund has owned $340 million in Israeli bonds, more than its combined $229 million in all other foreign government bonds, plus $230 million in Israeli stocks and a $1 billion commitment to Israeli private equity. The Intercept separately reported the state's Common Retirement Fund held $352 million in Israel bonds as of March 2024.
Nationally, demand for Israel Bonds has stayed strong. The Guardian reported that U.S. states and municipalities bought at least $1.7 billion in Israeli bonds since the October 7, 2023 attacks, and that Israel Bonds president and CEO Dani Naveh said the corporation had sold more than $5.7 billion worldwide over that span. The same report noted that Palm Beach County, Florida, residents sued their county over its investment of $700 million in local property taxes in Israeli bonds. JTA reported that some other local and state governments across the country are making record investments in Israeli foreign debt even as New York City pulls back.
Levine’s reversal also lands amid friction at City Hall, where Mayor Zohran Mamdani has criticized Israel, a dynamic the Times situates within the comptroller’s broader balancing act. Levine said his office is conducting an ongoing analysis of Israeli bonds going forward, leaving open whether the current decision holds as conditions in the region continue to shift.