
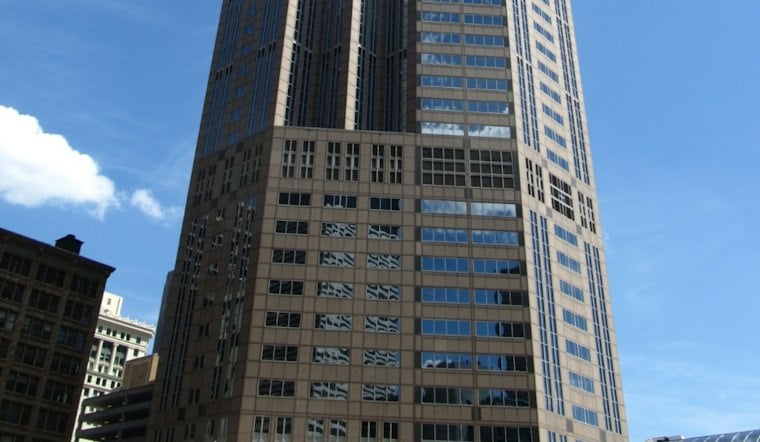
Israeli bondholders are set to decide Thursday whether to force Kohan Properties into immediate repayment of roughly $112 million in debt, a vote that could put the 65-story office tower at 311 South Wacker Drive and seven regional malls into creditors' hands years ahead of the bonds' 2030 maturity. The showdown comes after founder Mike Kohan was stripped of his authority and corporate presidency following a creditor's seizure of his ownership interest to satisfy a loan default.
The roughly $112 million in traded debt could be called for immediate repayment, according to The Real Deal, which reports that Kohan Properties changed hands without bondholders' consent after the creditor move against Kohan. Israeli bond filings cited by the outlet allege that ownership change itself breached the bond agreement, a claim that sits at the center of Thursday's vote. Senior bondholders are scheduled to convene at 4 p.m. Israel time, equivalent to 9 a.m. in Chicago, to decide the company's fate.
Two Paths: Seizure or a Softer Amendment
Bondholders have two options on the table. They can choose debt acceleration, which requires only a simple majority of votes cast to trigger default and lien enforcement, potentially allowing a trustee to seize the seven pledged regional malls along with 311 South Wacker Drive. Alternatively, they can approve an amendment adjusting the interest rate and redefining control, which needs a two-thirds supermajority to pass.
That proposed amendment would hold the coupon flat at 7.5 percent, waive rating downgrade penalties, and cap future interest-rate increases, per the same outlet's reporting. The stakes rose after Israeli credit rater Midroog downgraded Kohan Properties' grade on October 5. Kohan Properties did not immediately return requests for comment on its preparations for the bondholder decision, the report notes.
New Ownership, New Leadership
The company's ownership now looks nothing like it did a few months ago. Decama Finance sold its Kohan Properties stake for $6.4 million on October 8 to a venture tied to Amos Luzon's Amos Luzon Entrepreneurship and Energy Group, which now holds 60 percent of the company, while Alpha Gidurim holds the remaining 40 percent. CoStar reports Luzon's group paid $6.4 million for a company overseeing a U.S. portfolio that was valued at $684.1 million this past summer.
Ran Daniel has held the dual post of CEO and CFO since Kohan's removal in September, a dual role Kohan Properties formally introduced him into as the firm's new leadership. Luzon is publicly backing Daniel, saying he brings discipline, judgment and accountability to the company's next chapter and that he believes in the properties' potential and the teams working to strengthen them, the outlet reports. Daniel has struck a measured tone of his own, saying there is no single answer for every property and that the firm will make disciplined property-specific decisions and build confidence through consistent performance.
Eight Malls, Seven Pledged as Collateral
Kohan Properties has eight struggling regional malls across the nation, seven of which are pledged to the Israeli bondholders as collateral — the same seven malls that could be swept up if bondholders choose acceleration. Lenders to Mike Kohan have also surfaced claims reaching into seven of the firm's malls and four of its subsidiaries, claims the company says it is still examining.
A Separate Fight Over the Former Citadel Center
Not every Kohan property is entangled in Thursday's vote. 131 South Dearborn Street, the 1.5 million-square-foot former Citadel Center that a Kohan venture bought for more than $100 million in June, is not collateral for the bonds. But the building has its own legal troubles: an investor has filed a lawsuit alleging Mike Kohan wiped out a $20 million stake in the property through an unauthorized transfer, and on October 14, the preferred-equity backer on that deal claimed an unauthorized change of control in regulatory filings and demanded immediate redemption of its investment. Kohan Properties disputes that an improper change of control occurred there, though it acknowledged the lawsuit in an Israeli regulatory filing.
Kohan's rapid Chicago buying spree has already drawn scrutiny for the steep discounts behind it. The firm acquired 311 South Wacker Drive for $45 million, an 85 percent drop from its 2014 sale price of $302 million, and closed on the former Citadel Center for $137 million, a 76 percent discount from its 2020 debt valuation, according to The Real Deal's earlier reporting. Kohan also snagged control of the 28-story, 900,000-square-foot building at 33 West Monroe Street in January by buying the former owner's troubled $60 million loan at a reported $25 million price, financing that deal with a $12.6 million short-term loan carrying a 25 percent interest rate from Underground Lending.
That 33 West Monroe building carries its own baggage: the structure was just 44 percent leased earlier this year, well below the roughly 72 percent downtown Chicago average, and the Baptist Theological Union filed an eviction complaint on July 10 against Kohan Retail Capital Funding Chicago, seeking possession of the land parcel beneath the tower along with more than $126,000 in back rent it says it's owed. However Thursday's vote in Tel Aviv shakes out, the decision will ripple through a Chicago office and retail portfolio already strained by discounted buys, leasing shortfalls, and unresolved litigation.