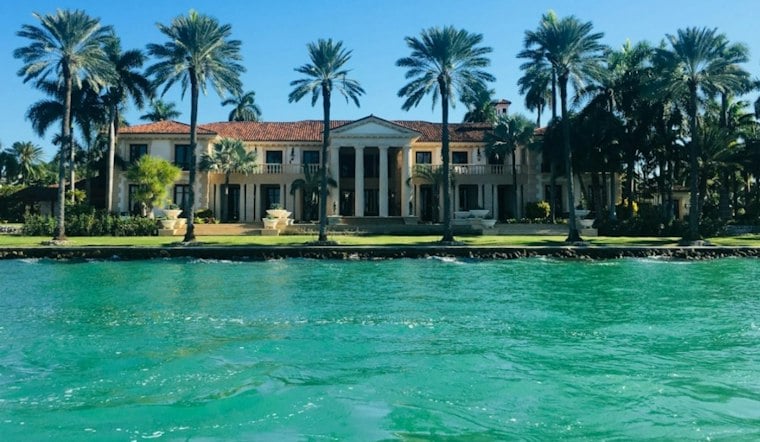
Miami-Dade County has already logged 24 home sales of $30 million or more through September, breaking the previous full-year record of 21 such sales set in 2025 — and it took just nine months to do it. Meanwhile, the county's overall home sales were down 2% year over year, single-family sales fell 4.7%, and total sales dropped 1% in August alone. The split tells a story of two very different Miami-Dade housing markets moving in opposite directions at the same time.
At the top and bottom of the price spectrum, Miami-Dade's housing market has held up, according to the Miami Herald, which reports that the Miami Association of Realtors found ultra-luxury homes and more affordable condos remained strong in September even as the middle of the market struggled. Existing condo sales overall rose just 1% year over year, but sales of condos priced between $300,000 and $400,000 jumped 14.5%. The reason, per the Herald's reporting, comes down largely to one thing: cash.
Why Cash Is King in Both Directions
Buyers of ultra-luxury homes and buyers of more affordable condos often have something in common — they're frequently paying cash, which insulates both groups from swings in mortgage rates. Mortgage rates were hovering around 7.5% as of the reported period, their highest level in almost three years, according to the Herald's report, and high rates likely contributed to Miami-Dade's declining home sales overall by pushing some potential buyers to delay purchasing altogether.
Nearly 38% of Miami-Dade home sales last month were made in cash, compared with a 27% national average, and the Miami metro area leads the nation in cash sales according to Miami Association of Realtors data cited by the Herald. Existing condo sales in the county were nearly half cash in September, while more than a quarter of single-family home sales closed the same way. At the very top of the market, 82% of condo purchases priced at $1 million or more were made in cash last year, per the Miami Association of Realtors.
The $300,000 Condo Catch
The affordable condos driving that 14.5% sales jump tend to be older buildings, and that's not incidental — it's often the reason buyers there need cash in the first place. Condos in the $300,000-to-$400,000 range are frequently ineligible for mortgages because of their age and condition, according to the Herald's reporting.
That mortgage squeeze traces back to the 2021 collapse of Champlain Towers in Surfside, Florida, after which lenders began requiring stricter reviews of Florida condo buildings' financial and structural health. Those stricter reviews have led to more buildings being blacklisted by lenders and more buyers being denied mortgages outright, pushing cash-paying buyers toward the only units still available to them.
Florida’s post-Surfside rules reach beyond lender reviews. State law requires condominium buildings at least three habitable stories tall to undergo milestone inspections when they reach 30 years old, then every 10 years; associations also must arrange structural reserve studies for qualifying buildings. The rules have since gained a limited repair-related flexibility: Florida law allows eligible associations, with a majority vote, to temporarily reduce or pause reserve contributions for up to two annual budgets to fund repairs recommended by a milestone inspection. Those requirements can affect owners’ costs and a building’s appeal to financed buyers.
Condo financing depends not only on a buyer’s income and credit but also on whether the building qualifies for a loan program. Fannie Mae identifies unresolved critical repairs, structural or safety concerns and insufficient property insurance among reasons a condominium project may be ineligible for loans it buys. That does not bar every mortgage: lenders may offer loans outside Fannie Mae’s programs. But when a building fails project review, buyers can lose access to a large pool of conventional financing, narrowing the market for its units.
Foreign Buyers Fuel the Cash-Heavy Market
Foreign nationals represent a significant portion of Miami-Dade home buyers, and they more commonly buy in cash because U.S. mortgages are harder for them to secure. A July 2025 report from the Miami Association of Realtors found that foreign buyers purchased nearly half of Miami-Dade's new construction, pre-construction and existing condo sales over the preceding 18 months.
The international-buyer presence also fits a wider Florida pattern, though it should not be confused with the share of all Miami-Dade buyers. The National Association of Realtors’ 2025 report found that Florida was the most popular U.S. state among foreign homebuyers, attracting 21% of those buyers nationwide. That statewide measure covers a broader market and buyer pool than Miami-area new-construction sales, but it underscores how international demand is an established part of Florida’s housing landscape.
That international demand helps explain why the high end of the market has kept setting records even as rate-sensitive buyers sit on the sidelines. Miami-Dade's new $30 million-plus benchmark, reached in nine months instead of a full year, underscores just how insulated the county's luxury segment has become from the financing pressures squeezing everyone else.