

























































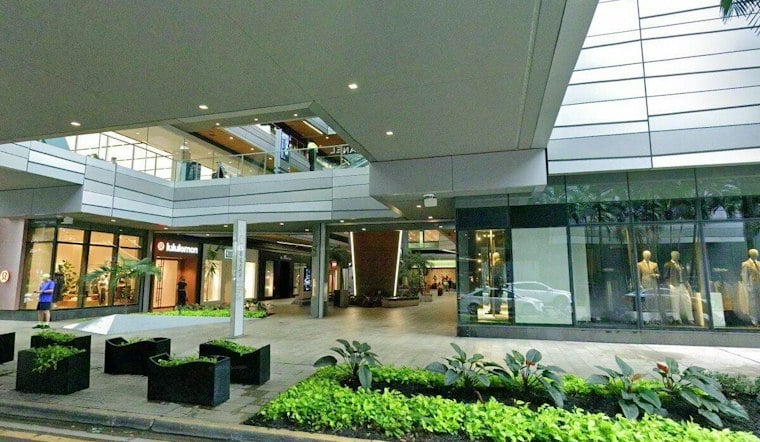
Dadeland Mall's owners are lining up a $555 million debt package that would refinance the sprawling Kendall shopping center and hand them nearly $200 million in cash, with the deal expected to close December 3. The refinancing covers the 1.5 million-square-foot mall at 7535 North Kendall Drive, a fixture of Miami-Dade County shopping for more than six decades.
Simon Property Group and Prime Property Fund are nearing the $555 million CMBS debt package, according to Commercial Observer. The report, authored by Julia Echikson, says Wells Fargo, Bank of Montreal and JPMorgan Chase Bank are originating a 10-year, fixed-rate, interest-only loan, a detail attributed in the reporting to Fitch Ratings. Fitch valued Dadeland Mall at $909 million and applied a 7 percent capitalization rate in its analysis, per the same account.
Of the $555 million total, $345 million will go toward refinancing existing debt on the property. Another $5.7 million is earmarked for landlord obligations and $4.5 million will cover closing costs, the outlet reports. That leaves just under $200 million in equity to be returned to the sponsors once the deal closes.
A Mall Still Pulling in Serious Sales
The refinancing comes as Dadeland Mall remains nearly fully occupied, as of September, the report notes. Over the year preceding August, the mall produced $892 million in total sales, with individual tenants posting striking numbers of their own: Apple generated $126 million in sales at the location, Macy's brought in $116 million, Saks Fifth Avenue notched $87 million, and Zara added $60 million, according to the same reporting.
The mall's tenant roster has also shifted toward newer retail names in recent years, now including Skims, Aritzia, Princess Polly, Salvatore Ferragamo and Dolce & Gabbana, per Commercial Observer's account. Dadeland's owners have invested $82.5 million over the past decade to renovate the four-story retail center, the outlet reports, with net operating income climbing to $66.4 million in the 12 months leading up to September, up from $61.6 million the prior year.
From Strip Center to Shopping Landmark
Dadeland's roots stretch back to October 1, 1962, when it opened as an open-air strip center with 400,000 square feet and 62 merchants, according to miamiherald.com. By the end of that decade, a rapidly expanding Dadeland had been enclosed and converted into a mall, the outlet reports. The transformation set the stage for decades of growth: in the 1990s, Dadeland Mall was described as the busiest shopping mall in the continental United States, per the same historical account.
Dadeland wasn't the only major mall to reshape South Florida's retail landscape in those decades. Aventura Mall opened in Northeast Miami-Dade in 1983, while Sawgrass Mills debuted in October 1990 and remains one of the largest malls in the country, miamiherald.com notes.
Simon's Broader South Florida Footprint
Simon Property Group, described in the Commercial Observer reporting as one of the country's largest mall owners, has been active elsewhere in the region too. The company bought the 500,000-square-foot Brickell City Centre mall in Miami for $512 million in 2025, and this year it filed plans to expand its 1.7 million-square-foot indoor mall in Boca Raton by redeveloping the nearby shuttered Sears department store, according to the same report.
Simon has also been active on the refinancing front outside Florida. The company lined up a $93 million mortgage from Goldman Sachs and Deutsche Bank against its Colorado Mills shopping center in the Denver suburb of Lakewood, Colorado, a 10-year loan described as carrying an interest-only coupon of 6.844 percent, according to a report from crenews.com.
A Simon Property Group representative did not immediately respond to a request for comment, Commercial Observer reports.





