

























































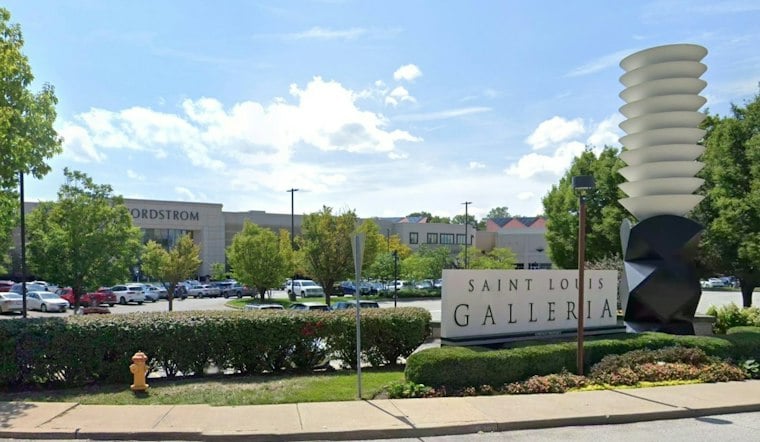
Saint Louis Galleria, the regional mall at 1155 Saint Louis Galleria in St. Louis, is now being marketed for sale, and the commercial mortgage-backed securities debt tied to part of the property is facing a potentially steep loss. S&P has estimated the mall's liquidation value at just $83 million, a staggering $383 million below its $466 million appraisal.
The figures come from CoStar News, which reports that GGP and Brookfield Corporation are both associated with the Galleria as the mall heads to market. Thomas Dobrowski, vice chairman of Newmark, is also named in connection with the listing, according to the same report. The gap between the appraised value and S&P's liquidation estimate underscores just how much uncertainty surrounds what the property could actually fetch in a sale.
A Mortgage Already Flagged for Default
The warning signs predate this month's listing. Back in May, the Galleria's $230 million mortgage loan entered special servicing after the borrower failed to make full April payments, amid declining occupancy, according to the St. Louis Business Journal. The outlet's reporting also found that the mall's occupancy fell and revenue declined after the pandemic, a slide that has only deepened the pressure on its debt.
Large sections of the Galleria's leases expired last year, and more are set to expire over the next two years, the Business Journal's report notes. That wave of lease expirations compounds the challenge facing whoever ends up owning the property, since filling vacant storefronts in a mall already carrying distressed debt is no small task.
Redevelopment Efforts Underway Despite the Debt Trouble
Not everything at the Galleria points downward. The former Nordstrom anchor space is being redeveloped as a Dick's House of Sport, per CoStar's reporting, a sign that at least part of the property is drawing fresh investment even as its mortgage struggles.
Richmond Heights officials, meanwhile, are pursuing mixed-use development as the Galleria's troubles mount, with the stated goal of diversifying the city's revenue sources, the Business Journal reported in a separate piece. A $200 million apartment complex with a Life Time Fitness center could begin construction this year, according to that report, suggesting the area around the mall may evolve regardless of how the sale plays out.
A Shaky Mall Debt Market Nationwide
The Galleria's predicament fits into a broader, uneven picture for mall debt across the country. Green Street has reported that U.S. mall values rose 13% year over year, the strongest increase of any commercial property type, according to Yahoo Finance. Yet that same report found Morningstar tracking 182 malls backed by 423 CMBS loans with nearly $42 billion in balances, of which 92 loans totaling $8.7 billion sat with special servicers.
Distress in retail CMBS has kept building in recent months. CRED iQ flagged $700 million of retail debt as newly delinquent or newly in special servicing in October, part of a wider $4.5 billion in conduit and single-asset, single-borrower debt newly flagged that month, 93% of which was past maturity or within six months of it, according to CRED iQ. Separately, cmbs.news data from October showed retail CMBS loans maturing this year totaling $3.1 billion across 143 loans, with nearly half marked distressed.
Other trackers paint a similar picture. Trepp's overall CMBS special-servicing rate reached 11.49% in September, up seven basis points, while Connect's August review put the retail special-servicing rate at 13.60%, according to data compiled by CRE Terminal. That same compilation found retail, lodging, and multifamily special servicing rising in September even as office and industrial declined.
Other Malls Facing Similar Debt Strain
The Galleria isn't an isolated case. The $325 million loan on Fresno Fashion Fair went 30 days delinquent ahead of its Nov. 1 maturity, even though that mall was 97.6% occupied, CRED iQ's October report found. And holders of the safest debt tranche tied to New York's Palisades Center mall lost more than $70 million last year, according to CRE Daily, which also reported that more than 30 top-rated single-asset, single-borrower CMBS tranches now trade below 85 cents on the dollar, citing Bloomberg data.
Those comparisons suggest that even well-occupied malls aren't immune to the maturity crunch hitting commercial mortgage debt nationwide. For Richmond Heights and the Galleria specifically, the coming months will determine whether a sale can close the gap between a $466 million appraisal and an $83 million liquidation estimate, or whether that shortfall becomes the defining number in the mall's next chapter.





